
How a Personal Lender Expanded Its Buy Box Without Adding Risk
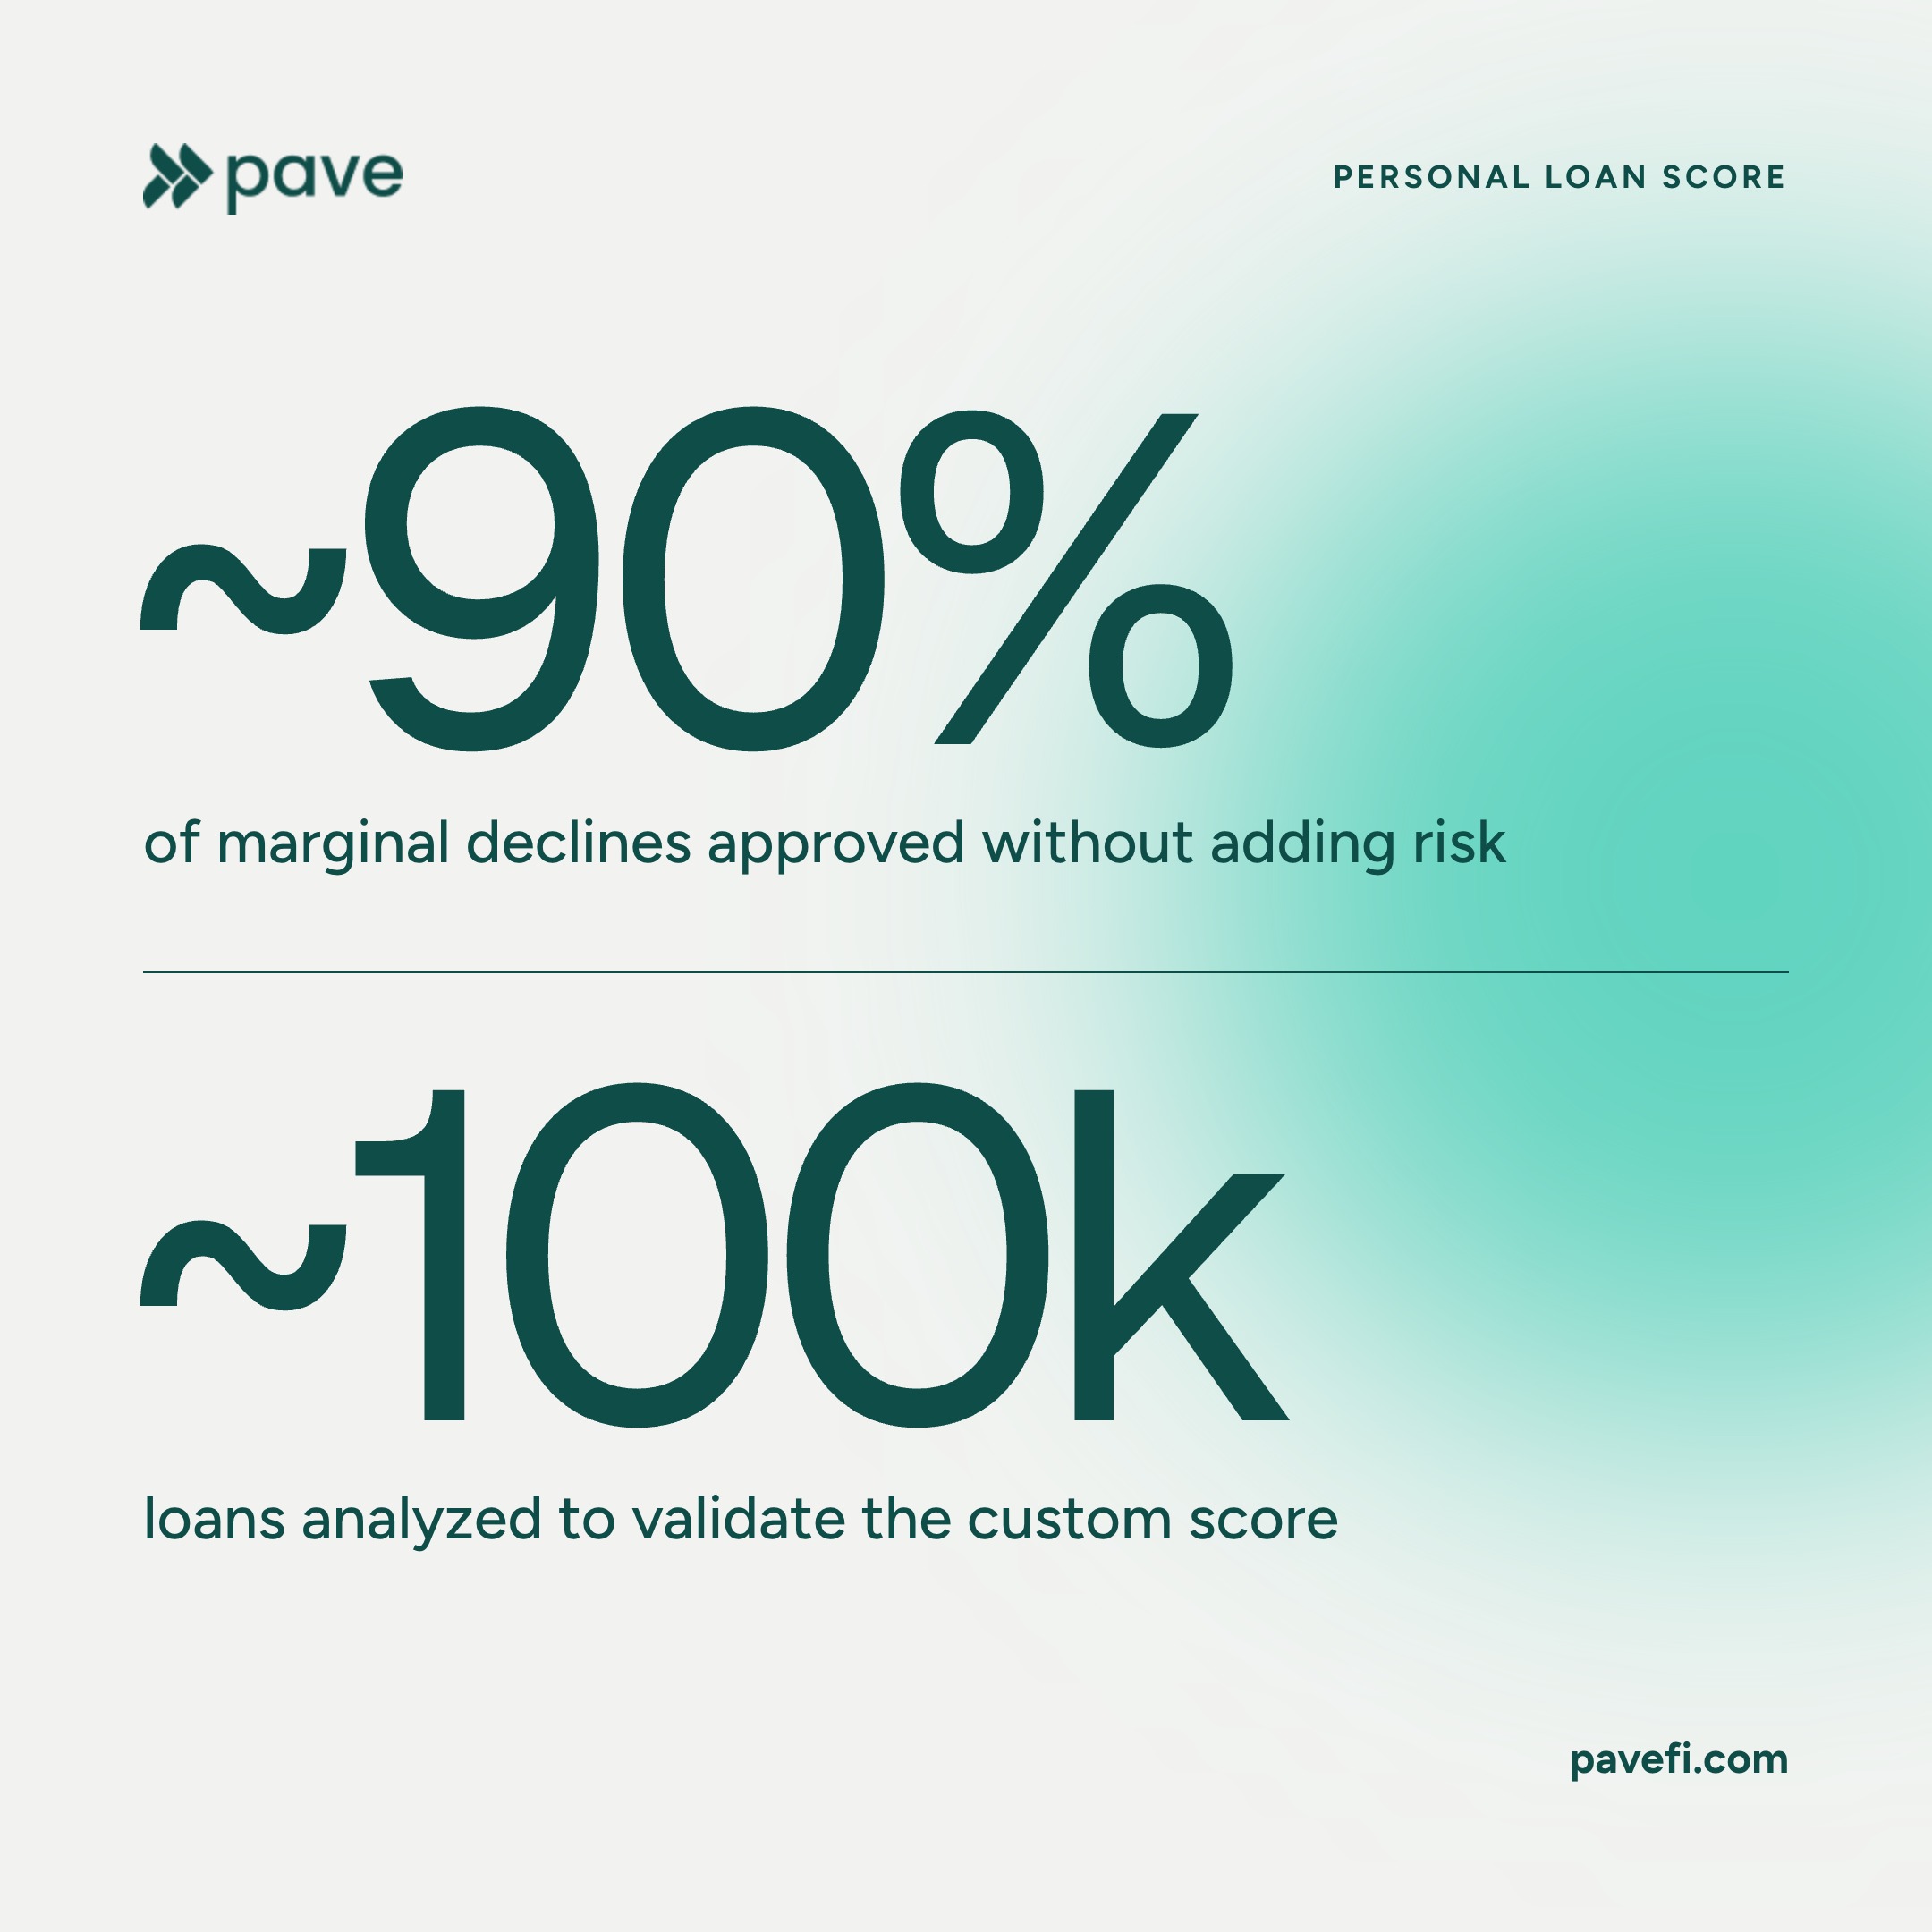
Pave helped a personal loan provider identify which marginal declines were actually approvable, enabling the lender to approve roughly 90% of that population without adding risk.
Challenge
For a personal loan provider, growth only works if credit performance holds. Expanding approvals without a sharper read on risk creates losses that outweigh the incremental volume.
The lender’s existing model helped sort applicants by risk, but left a gray area: marginal applicants who were close to approval, yet still treated as declines. Some of those borrowers looked risky through traditional credit attributes, even though their cashflow behavior suggested they could repay.
The lender needed a more targeted way to decide which marginal declines were actually approvable before widening access.
Solution
Pave partnered with the lender to build a custom Personal Loan Score around its own performance data and underwriting workflow.
- Portfolio-specific model training: The score was trained on the lender’s historical loan performance, making it specific to the lender’s book rather than a generic market score.
- Consumer-permissioned cashflow data: Pave used bank transaction and balance data to add a real-time view of borrower financial behavior, including signals like income stability, cash reserves, fee activity, balance trends, spending pressure, and repayment capacity.
- Ongoing performance feedback loop: As the lender shares performance data back to Pave, both teams will monitor results, refine the model, and keep the score aligned with real portfolio outcomes over time.
Results
Pave’s analysis showed that cashflow data could separate risk inside the lender’s marginal-decline population, turning a gray area into a clearer approval opportunity.
- ~100k loans analyzed: The custom score was validated against historical loan performance and cashflow data.
- 90% of marginal declines approved: More near-miss applicants could move forward without adding risk.
Conclusion
The lender did not need another generic credit score. It needed a sharper way to decide which marginal applicants were actually approvable.
By building a custom Personal Loan Score on the lender’s own performance data and applicant cashflow, Pave helped the lender approve more near-miss borrowers while keeping risk aligned with real portfolio performance.
See what a score built for your book can do
Off-the-shelf scores you can deploy today, sharpened by every lender on the network.
Explore Use Cases
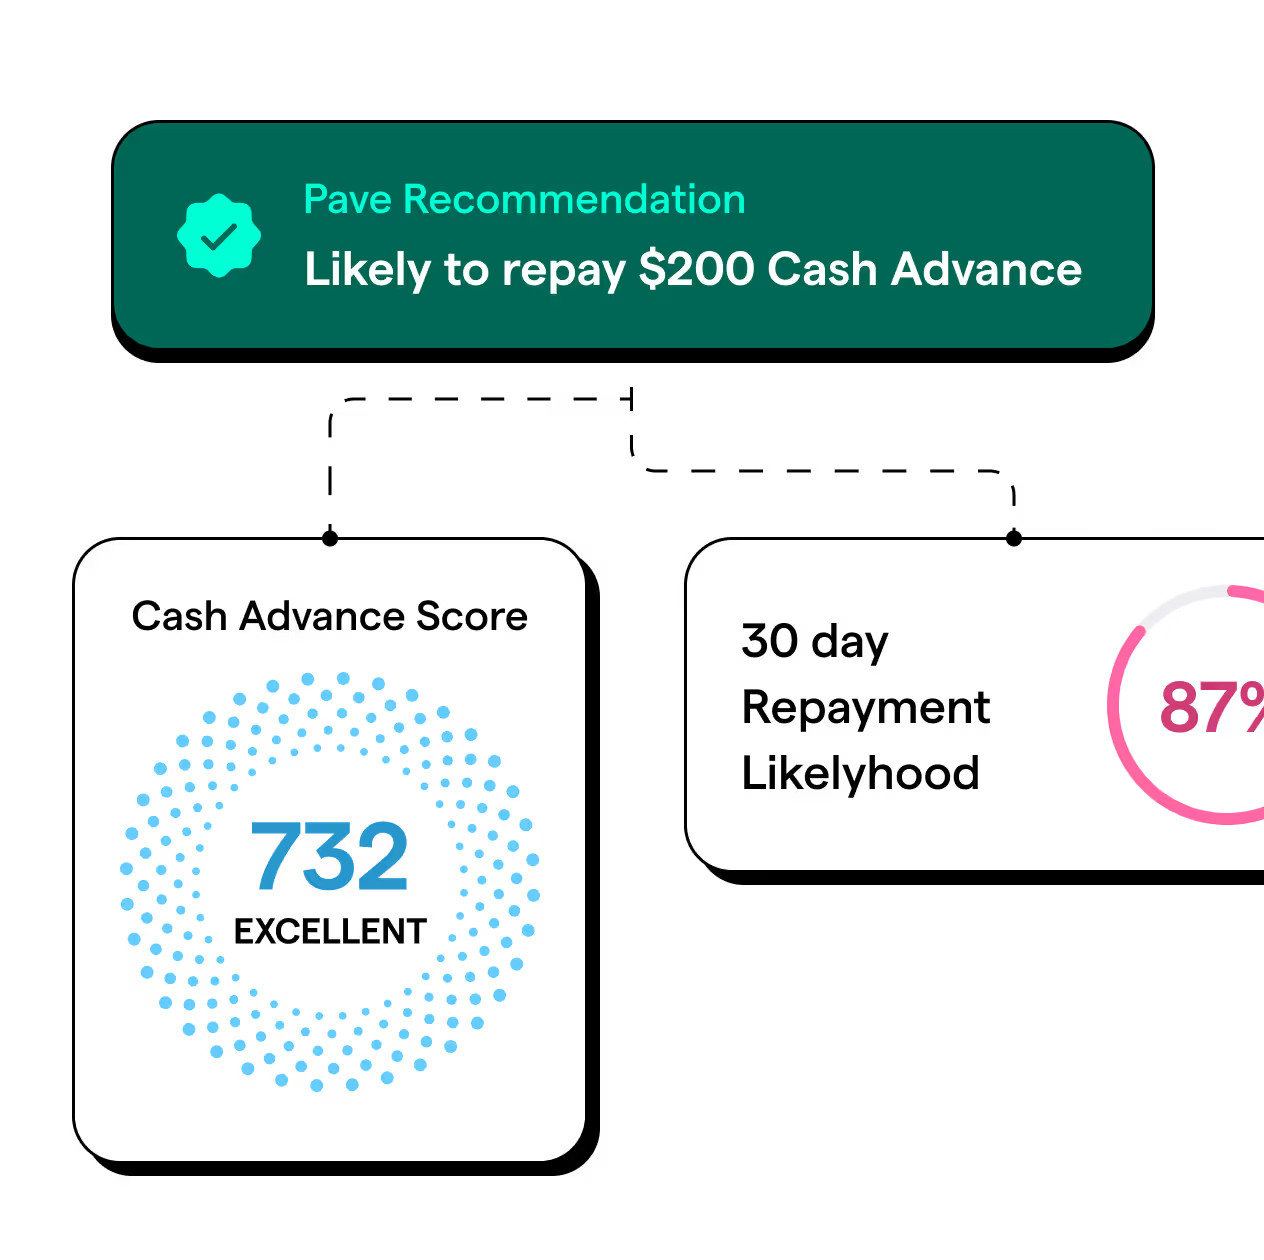
Cash Advance
Score users to increase approvals, advance amounts, and improve repayments.
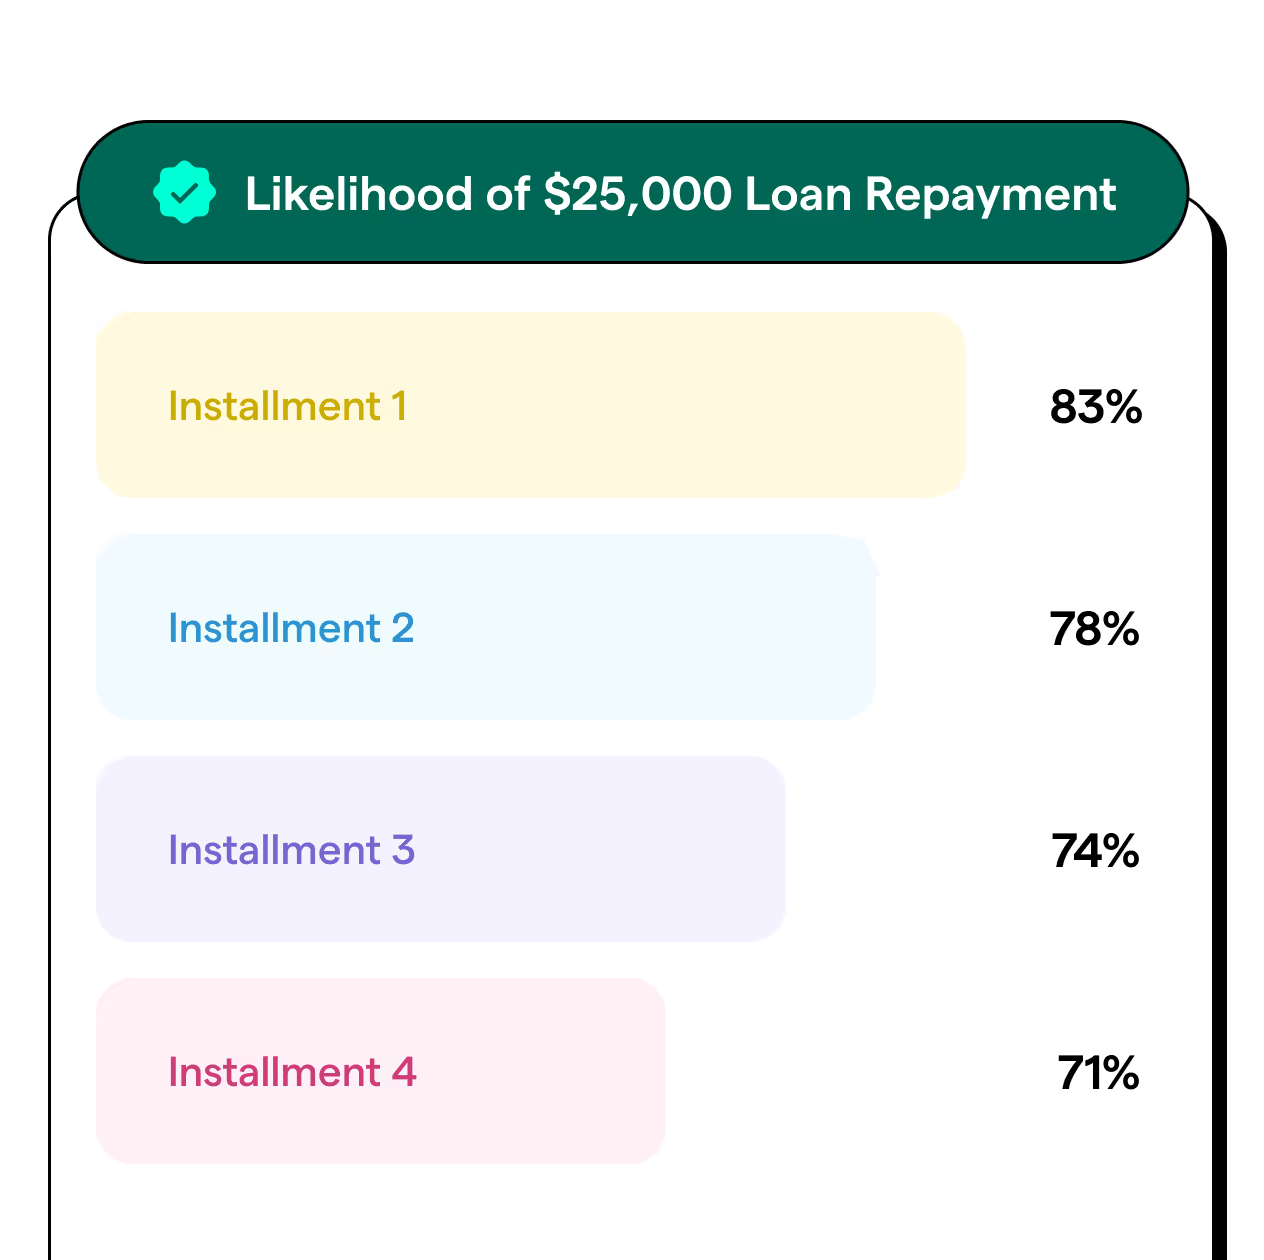
Personal Loans
Identify users with high likelihood of making the first 4 payments to reduce delinquencies.
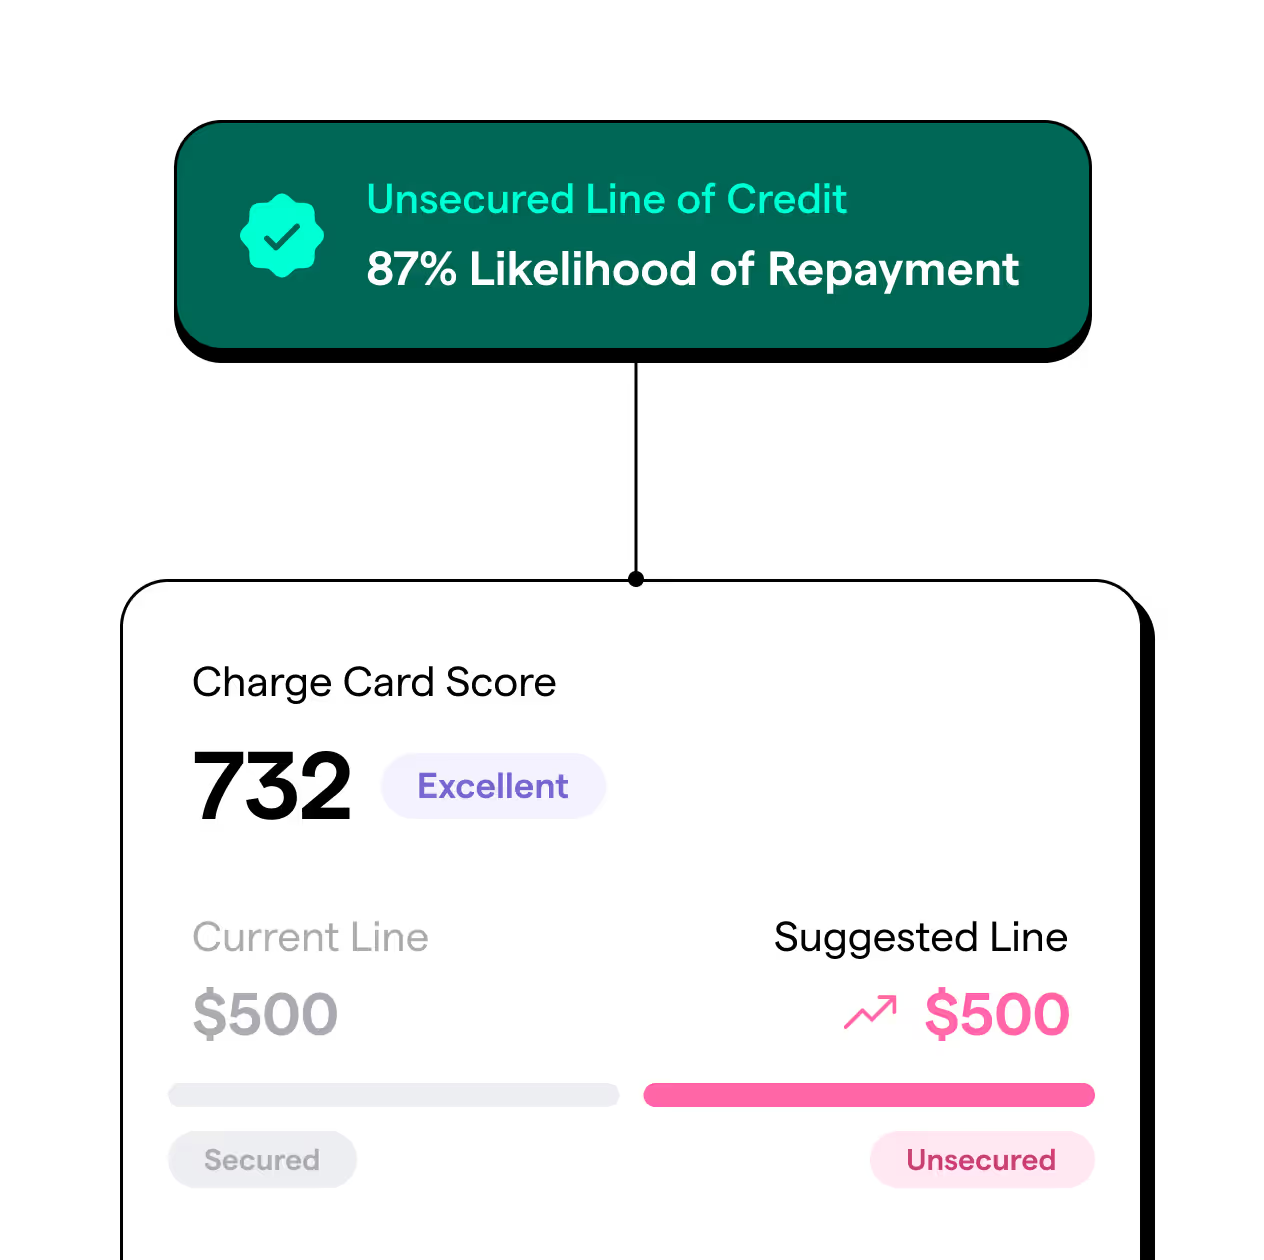
Charge Cards
Graduate users to higher secured or unsecured limits based on increased affordability.
Credit Cards
Set dynamic credit limits based on users' income and affordability.
Drive growth with Cashflow-driven Analytics
Use our Cashflow-driven Attributes and Scores to provide timely, borrower-specific insights tailored to your lending criteria. Make informed decisions that enhance approval rates and loan performance.